Author: Andy Mohr Toyota Team
Deciding whether to finance or lease your new Toyota depends heavily on your daily driving routine. If you rack up miles commuting down U.S. Route 36 toward the Indianapolis International Airport, financing often makes sense, while leasing provides flexibility for families taking shorter weekend trips to Avon Town Hall Park. For years, Andy Mohr Toyota has been a steadfast part of the community, serving as a reliable, long-term automotive partner for drivers across Avon, Brownsburg, Indianapolis, Plainfield, and Carmel. We proudly pair this trusted local experience with our proven expertise in servicing and maintaining Toyota vehicles, ensuring your car is ready for any weather.
Key Takeaways (TL; DR)
- Credit Scores Drive Rates: Your financial history plays a massive role in the interest terms you qualify for. Securing a strong score means less money spent on interest over the life of the loan, leaving more room in your budget for weekend runs to Avon Commons.
- Toyota Financial Services (TFS): Financing directly through Toyota often unlocks competitive terms and exclusive regional promotions. Applying for pre-approval online before driving down U.S. Route 36 streamlines the entire process.
- Financing vs. Leasing: Traditional financing builds equity until you own your vehicle outright—ideal if you rack up high mileage commuting to the Indianapolis International Airport. Leasing, on the other hand, typically yields lower monthly payments and lets you upgrade to a new RAV4 Hybrid or Camry every couple of years.
- Flexible Lease-End Choices: When a Toyota lease concludes, you are not locked into a single path. Depending on your current lifestyle, you can buy the vehicle, lease a brand-new model, or simply turn it in.
- Exclusive Rebate Programs: Toyota frequently offers targeted savings for recent college graduates and military personnel. If you qualify, these special incentives can significantly reduce the overall cost of your next vehicle.
- Upfront Preparation Matters: Before heading out to explore your options, take time to gather your trade-in documents, check your credit, and establish a realistic budget. Knowing your numbers beforehand ensures a confident, stress-free decision.
How Toyota Vehicle Financing Works
Financing a vehicle simply means securing a loan to cover the purchase price, which you repay with interest over a set schedule known as your loan term—typically ranging from 36 to 72 months. What this means for Avon drivers is that you can spread out the cost of a dependable ride, making it much easier to budget for daily commutes along U.S. Route 36 or frequent trips to the Indianapolis International Airport. Whether you secure funds through Toyota Financial Services (TFS), a national bank, or a local Hendricks County credit union, each monthly payment puts you on the direct path to outright ownership.
As you make those predictable payments, you actively build equity—the actual cash value of the vehicle that belongs to you rather than the lender. Once the loan balance hits zero, the institution transfers the official title into your name. Think of it this way: if your family regularly racks up high mileage hauling gear to Avon Town Hall Park or packing up a Toyota Highlander for weekends near the Haunted Bridge, taking out a loan means you never have to worry about the strict mileage limits that come with leasing. Plus, you have the total freedom to permanently customize your SUV or truck with genuine accessories like all-weather floor liners and roof racks right from day one.
How Toyota Financial Services (TFS) Operates

Once you select a vehicle for your daily commute down U.S. Route 36 or family outings at Washington Township Park, Toyota Financial Services (TFS) steps in to streamline the funding. As the automaker's dedicated lending arm, TFS integrates directly with the showroom to provide customized auto loans and lease agreements. You can easily jump-start the process by submitting an online pre-approval application from your couch, bypassing much of the traditional paperwork before you even arrive.
When reviewing your application, TFS evaluates standard financial metrics like your credit history and current income. Because these details dictate your eligibility, the available offers—including down payment requirements and monthly structures—will vary by credit profile. What this means for Avon drivers is a highly personalized financing path rather than a rigid, one-size-fits-all approach.
Working directly through the manufacturer also opens doors to exclusive factory incentives. For instance, securing a promotional Annual Percentage Rate (APR) on a new Toyota Camry Hybrid over a standard 60-month loan can drastically lower your overall interest costs compared to typical bank rates. TFS frequently provides targeted loyalty bonuses, military rebates, and college graduate programs that outside lenders simply do not carry.
How Does Leasing a Toyota Work?
When you lease a vehicle like a new Toyota RAV4, you are essentially paying for the portion of the car you use rather than its total purchase price. Standard lease agreements typically run for 24 to 36 months and include a set mileage allowance, often between 10,000 and 12,000 miles per year. Your monthly payment is largely based on depreciation. This is calculated by taking the vehicle's initial sticker price and subtracting its estimated worth at the end of the contract term—a figure called the residual value. Alongside depreciation, your monthly bill includes standard fees, local taxes, and a "money factor," which serves as the leasing industry's equivalent of an interest rate.
Here is a quick breakdown of how that math works: If a vehicle costs $35,000 new and has a projected residual value of $20,000 after three years, your lease payments only cover that $15,000 difference rather than the full sticker price. What this means for Avon drivers commuting down U.S. Route 36 or heading out to The Shops at Perry Crossing in Plainfield is a predictable monthly budget that is often lower than a traditional auto loan. At the end of the term, you simply return the vehicle to the dealership, providing a straightforward transition into a newer model without the need to negotiate trade-in values.
Navigating Your Toyota End-of-Lease Options
As your contract winds down, you generally have three straightforward paths: buy your current vehicle, trade it in for a new model, or simply return the keys. For drivers around Avon and nearby Plainfield, this flexibility means you can seamlessly adapt your ride to fit a changing lifestyle without any unnecessary hassle. Whether your daily commute has shifted or your family has outgrown your current car, here is how you can handle the transition.
- Purchase Your Leased Toyota: If you love your current vehicle, you can buy it outright for the exact residual value listed in your original contract. Because this buyout price was locked in years ago, it often costs significantly less than purchasing a comparable used car at today's market rates. This makes strong financial sense if your routine drives along Ronald Reagan Parkway have kept your car in pristine condition.
- Upgrade to a New Toyota: Ready for the newest technology or a different body style? You can turn in your current vehicle and start a fresh lease or finance agreement. For example, if you started with a Corolla sedan but now need the extra cargo space of a RAV4 for family outings at Washington Township Park, this path lets you easily transition into a model that fits your current life.
- Return Your Vehicle: You always have the option to simply walk away at the end of your term. Just remember to schedule a standard end-of-lease inspection roughly 15 to 60 days before your turn-in date. Doing so gives you a clear picture of any excess wear, tear, or mileage overages so you can address them before handing over the keys.
Deciding Between Financing and Leasing a Toyota

How you pay for your vehicle impacts your budget along U.S. 36. What this means for Avon drivers is a choice between long-term equity or lower initial costs. Financing leads to ownership, while a 36-month lease keeps you under the 2-year/25,000-mile ToyotaCare coverage longer. If you commute toward Indianapolis International Airport, annual mileage limits might make the decision.
| Feature | Financing a Toyota | Leasing a Toyota |
|---|---|---|
| Ownership | The title transfers to your name once the auto loan is fully paid. | The leasing company retains ownership throughout the entire contract. |
| Monthly Payments | Usually higher, as installments go toward the total purchase price of the vehicle. | Generally lower, because you only pay for the car's expected depreciation during the lease term. |
| Upfront Costs | Typically involves a down payment, state taxes, and standard registration fees. | Usually requires the first month's payment, standard acquisition fees, and occasionally a security deposit. |
| Customization | Complete freedom to add aftermarket parts, change the paint, or upgrade the interior. | The vehicle must be returned in factory condition; permanent modifications are not allowed. |
| Mileage | No restrictions—drive as many miles as you want without financial penalty. | Strict annual mileage caps apply (often 10,000 to 12,000 miles), with per-mile overage fees. |
| Wear & Tear | Dents and scratches only affect your future trade-in or resale value. | Lease-end inspections are required, and excessive wear results in out-of-pocket charges. |
| End of Term | You keep the car, sell it privately, or trade it in for a new model. | Simply return the keys, buy out the lease, or start a new contract. |
What Shapes Your Toyota Lease or Loan Terms?
When you're ready to secure financing for a fuel-efficient Toyota RAV4 Hybrid or a spacious Sienna for family outings at Washington Township Park, the final numbers aren't just pulled from thin air. Lenders evaluate a mix of your personal financial history alongside the specific vehicle you are buying. What this means for Avon drivers is that understanding these variables beforehand helps you structure a monthly payment that comfortably fits your lifestyle, whether your routine involves a daily commute down U.S. Route 36 or weekend bulk-shopping runs to the local Costco.
- Credit Score: Your credit history acts as a primary indicator of risk for lenders. A strong score typically unlocks the most competitive Annual Percentage Rates (APRs), directly reducing how much extra you pay over the life of the vehicle.
- Down Payment: Bringing more cash to the table upfront immediately lowers your principal balance. For example, putting an extra $2,000 down on a new Toyota Camry not only shrinks your monthly payment but also cuts down the total interest accrued over the years.
- Term Length: Auto loans generally run in intervals like 36, 48, 60, or 72 months. Stretching the term out will give you a smaller monthly bill, but keep in mind that a longer timeline means paying more in overall interest charges.
- Vehicle Price and Type: The MSRP and configuration of the Toyota you choose set the baseline for your financing. Plus, opting for a brand-new vehicle often opens the door to exclusive factory finance promotions that aren't usually available for older models.
- Debt-to-Income Ratio (DTI): Banks look at your gross monthly income compared to your current recurring debts, like a mortgage or student loans. This calculation assures the lender—and you—that adding a car payment won't overextend your budget as you manage daily expenses around Hendricks County.
Are There Special Toyota Incentive Programs I Can Qualify For?
Toyota provides specialized financing and lease programs designed to lower your overall vehicle cost, provided you meet the specific qualification criteria. What this means for Avon drivers is that upgrading to a fuel-efficient Toyota Prius for your daily U.S. Route 36 commute might be far more accessible than you expect. By utilizing these targeted incentives through Toyota Financial Services, eligible buyers can secure exclusive rebates or more favorable lease terms. For example, if you just earned your degree and accepted a position near Indianapolis International Airport, applying a graduate rebate can significantly offset the initial cost of a new Corolla Cross.
- Toyota College Graduate Program: Recent alumni who supply proof of degree completion within the last two years, alongside verifiable upcoming or current employment, can take advantage of specialized rebates on a variety of new models.
- Toyota Military Rebate: As a gesture of gratitude, eligible active-duty U.S. military personnel, inactive reservists, retirees, veterans discharged within the past 12 months, and their household spouses qualify for unique purchasing discounts.
- Brand Loyalty Benefits: Current owners trading up to a modern option like the RAV4 Hybrid frequently receive loyalty lease or finance benefits for remaining in the Toyota family. Trusted automotive resources like Edmunds consistently highlight how utilizing manufacturer loyalty offers reduces your total cost of ownership.
- Regional Midwest Promotions: Periodically, Toyota releases area-specific incentives. This means you might discover seasonal lease deals tailored strictly to central Indiana residents, hitting the market right when you need a capable SUV for winter outings at Washington Township Park.
Steps to Secure Your Toyota Lease or Auto Loan

Starting your auto loan or lease process is straightforward, whether you initiate the paperwork online from home or complete it in person. For families managing busy schedules around Avon—like running kids to Washington Township Park or commuting to Indianapolis International Airport—knowing exactly what financial steps to expect saves valuable time. By utilizing Toyota Financial Services, drivers gain access to competitive annual percentage rates (APRs) and flexible term lengths tailored to local budgets. That means you can focus entirely on picking the right model, like a spacious Grand Highlander or an efficient Camry Hybrid, rather than stressing over the fine print. As a quick tip: checking your estimated rates through a soft credit pull beforehand protects your score and can reduce your overall dealership visit by an hour or more compared to walking in blind.
- Check Your Pre-Qualification Status: Begin by requesting preliminary terms. This step uses a soft credit inquiry, allowing you to see estimated interest rates and borrowing limits without temporarily lowering your credit score.
- Organize Essential Documents: When you are ready to move forward, gather a valid Indiana driver’s license, recent proof of income (such as your last two pay stubs), verification of your local residence (like a recent utility bill), and active auto insurance information.
- Submit the Official Application: To officially fund your new Toyota, you will need to complete a formal credit application. This action requires a hard credit inquiry to lock in your exact interest rate and final approval amount.
- Review the Terms and Sign: Before you grab the keys, carefully verify the final APR, the exact length of your loan or lease (typically spanning 36 to 72 months), the scheduled monthly payment, and any elected protections like GAP coverage.
Should You Pay Cash or Finance Your Next Toyota?
Buying a vehicle outright means you take immediate ownership without paying a dime in interest. If you are eyeing a 2026 Toyota RAV4 Hybrid for your daily commute down U.S. Route 36, paying cash frees up your future monthly budget for family outings to Washington Township Park or shopping trips at Avon Commons. The trade-off, of course, is that parting with a large lump sum reduces your liquid savings. That matters for Avon drivers who want to keep emergency funds easily accessible for unexpected expenses. Fortunately, whether you hand over a cashier's check or take out a loan, your new vehicle still comes with ToyotaCare, providing no-cost factory scheduled maintenance for 2 years or 25,000 miles.
On the flip side, financing allows you to spread the vehicle's cost over a typical 36- to 72-month term, keeping your bank account flush for the unexpected. While you will pay interest over the life of the loan, holding onto those cash reserves offers valuable peace of mind and flexibility. Many families around Hendricks County prefer this route because it makes stepping into a spacious, three-row 2026 Toyota Highlander for weekend trips to the Haunted Bridge much more approachable. Ultimately, the right choice depends entirely on your personal goals and how comfortable you feel balancing a monthly auto payment against maintaining your bulk savings.
What Are the Pros and Cons of Each Payment Method?
Choosing between a lease or loan depends heavily on your daily mileage around Avon and how long you want the car. Financing builds equity over time, while leasing often lowers monthly costs. If you rack up miles on U.S. 36, buying makes sense; otherwise, a lease offers flexibility.
Pros of Financing a Toyota
- Complete Ownership: Once that final payment clears, the vehicle is 100% yours. You can keep driving it payment-free, sell it, or pass it down to a family member.
- Unlimited Mileage: Drive as much as you want without worrying about overage fees. If your daily commute takes you from Brownsburg to Indianapolis down Ronald Reagan Parkway, buying removes those mileage boundaries completely.
- Total Customization: Want to add a specialized bed rack to your Tacoma i-FORCE MAX or swap out the wheels? When you finance, you can modify the vehicle exactly to your tastes without penalty.
- Building Equity: Every payment you make on a Highlander or RAV4 builds equity. Because Toyota models are renowned for holding their value, that equity can eventually be used as a strong down payment for your next vehicle.
Cons of Financing a Toyota
- Higher Monthly Costs: You are paying for the entire total cost of the vehicle rather than just its depreciation. This typically results in a higher monthly payment compared to leasing the exact same model.
- Post-Warranty Repairs: New Toyotas come with a 3-year/36,000-mile basic warranty and ToyotaCare covering routine maintenance for the first 2 years or 25,000 miles. Once those protections expire, you handle repairs out of pocket.
- Market Depreciation: While Toyota vehicles typically retain value well, all cars depreciate. You bear the risk of fluctuating market values when it is finally time to sell or trade.
Pros of Leasing a Toyota
- Lower Monthly Payments: You only pay for the vehicle’s depreciation during the lease term. For instance, if a Camry depreciates 45% over three years, you only finance that 45% (plus rent charges), keeping your monthly outgoing cash significantly lower than buying it outright.
- Frequent Upgrades: Leasing allows you to step into a new vehicle every two to three years. You’ll always have access to the latest Toyota Safety Sense technology, which is a massive advantage when navigating tight parking spots at Avon Commons or Costco.
- Streamlined Maintenance: Most lease terms only last 36 months, meaning the car stays under the factory bumper-to-bumper warranty for the duration of the contract. This virtually eliminates surprise repair bills.
- Hassle-Free Returns: At the end of the term, you simply hand the keys back to the dealership. There is no need to haggle over trade-in values or try to find a private buyer.
Cons of Leasing a Toyota
- No Ownership Stake: You are essentially renting the vehicle long-term. When the lease ends, you won't have an asset to sell or trade unless you choose to buy it out.
- Mileage Restrictions: Contracts typically limit you to 10,000 or 12,000 miles a year. If you frequently drive down to Indianapolis International Airport or take long weekend road trips, exceeding this cap will result in per-mile penalty fees at turn-in.
- Wear and Use Charges: You must return the vehicle in good condition. Excessive scratches from hauling gear to Washington Township Park or stained upholstery could trigger extra reconditioning fees.
- Early Termination Fees: Breaking a lease contract before the agreed-upon end date can be incredibly expensive, heavily limiting your flexibility if your financial situation or lifestyle suddenly changes.
How to Maximize Value on Your Next Toyota in Avon

For families running errands around Avon Commons or commuters making the daily drive down Ronald Reagan Parkway, a dependable vehicle is practically a necessity. Balancing that need with your household budget takes a bit of strategy. What this means for Avon drivers is that doing some focused homework before walking onto the lot ensures a transparent, comfortable financial arrangement. By preparing your credit, timing your purchase right, and understanding your lending options, you can significantly lower your overall automotive costs.
- Review Your Credit Report Early: Well before test-driving a new Toyota Camry, pull your credit history. Correcting a simple reporting error can bump your credit score up a tier, potentially qualifying you for much more favorable interest rates.
- Shop Around for Financing: Secure a pre-approval quote from a local credit union or bank in Hendricks County, then see if the dealership can beat those terms. Having a baseline financing offer in hand gives you confidence and a clear point of comparison.
- Focus on the Total Vehicle Price First: It can be tempting to focus entirely on hitting a specific monthly payment, but you should always agree on the out-the-door cost of the vehicle before discussing loan structures. This keeps the actual negotiated price of that spacious Toyota Highlander entirely separate from the financing mechanics.
- Master the Key Numbers: For traditional financing, pay close attention to the Annual Percentage Rate (APR) and the loan term length. If you choose to extend a loan from 60 to 72 months, your monthly payment will drop, but the total interest paid over the life of the loan will climb considerably. For leases, know the capitalized cost (the agreed-upon value of the vehicle) and the money factor (the lease interest rate).
- Leverage the Calendar: Timing matters. End-of-month and end-of-quarter transitions often align with fresh manufacturer incentives. Similarly, resources like Edmunds note that shopping late in the year or during late summer—when next year's inventory typically starts arriving—can yield excellent opportunities on outgoing models.
Frequently Asked Questions (FAQs)
What should I look for in the finance paperwork?
Andy Mohr Toyota prioritizes a transparent, no-haggle buying experience, so our team will walk you through every detail of your agreement. We ensure you fully understand your loan terms before you hit U.S. Route 36 in your new Toyota hybrid.
How does Andy Mohr Toyota ensure accurate billing and address questions after signing?
Because we are a family-owned dealership dedicated to customer satisfaction, Andy Mohr Toyota provides a transparent, no-haggle process from start to finish. If you ever need clarification on your paperwork after returning home to Plainfield, our knowledgeable team is always available to review your contract with you.
How does Andy Mohr Toyota review optional protections and accessories during the contracting process?
Our knowledgeable team carefully explains any optional protections that might benefit your commutes to Indianapolis International Airport or family trips to Washington Township Park. Andy Mohr Toyota ensures every addition is clearly outlined as part of our transparent, no-haggle buying experience.
How can I ensure I understand all fees before signing?
The friendly sales team at Andy Mohr Toyota actively reviews every line item with you before you sign. We built our family-owned dealership on a transparent, no-haggle buying experience, meaning we take the time to answer all your pricing questions upfront.
What online purchasing options does Andy Mohr Toyota provide?
Andy Mohr Toyota embraces innovation through our Mohr to Your Door program, which creates a seamless online purchasing path. We offer free home delivery within 150 miles, so you can receive your new vehicle right at your driveway in Avon or Brownsburg.
How does Andy Mohr Toyota support the local community?
We are deeply rooted in our community and actively reflect our core values of service and generosity by supporting local initiatives. Andy Mohr Toyota proudly partners with programs like ArtScape @ Your Library and the Toys for Tots program to give back to the neighborhoods we serve.
About Andy Mohr Toyota
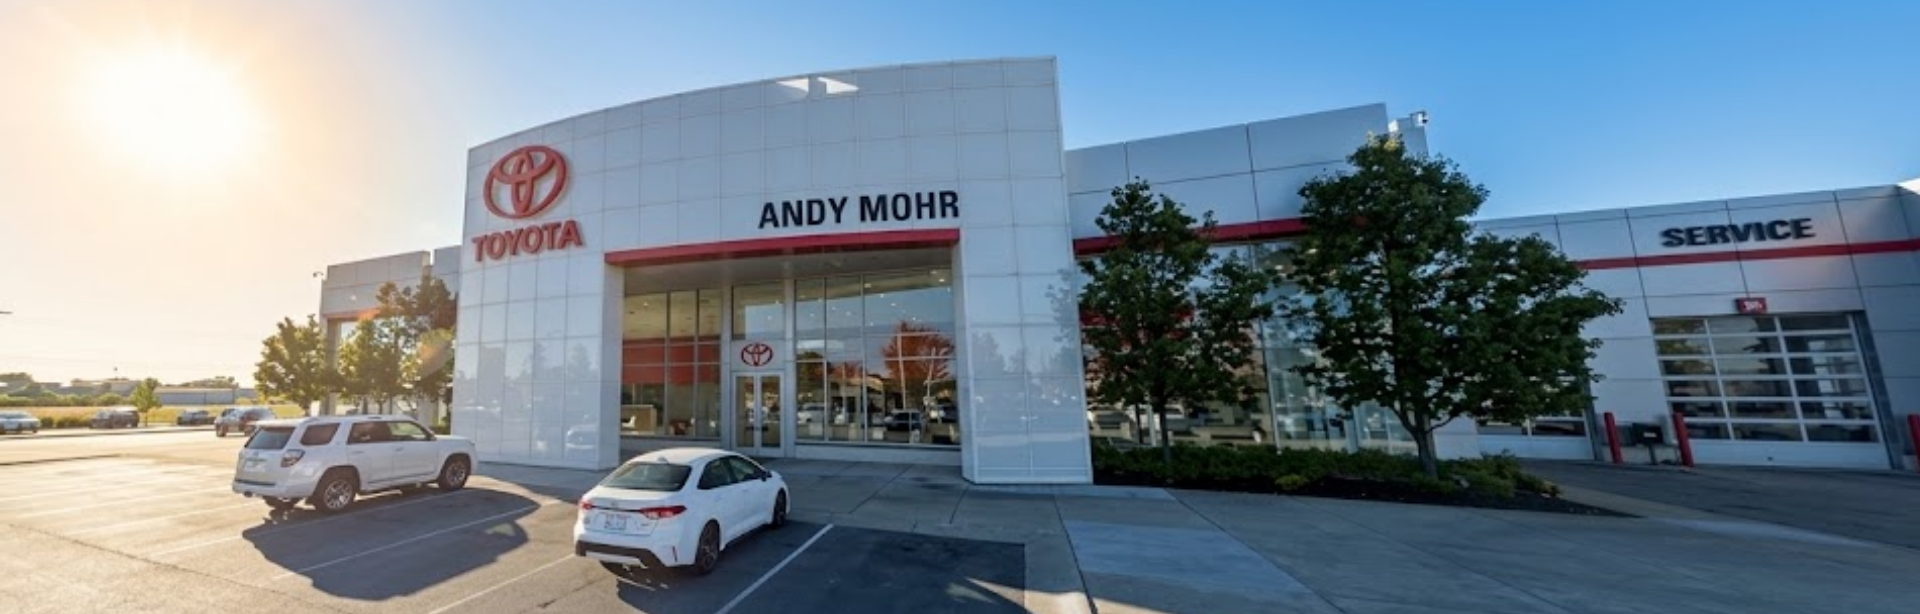
At Andy Mohr Toyota, established in 2005, we pride ourselves on being a family-owned dealership that prioritizes a transparent, no-haggle buying experience, supported by our knowledgeable and friendly sales team. Our commitment to customer satisfaction has earned us the prestigious Toyota President's Award, a testament to our dedication across every department. We embrace innovation with our Mohr to Your Door program, offering a seamless online purchasing path and free home delivery within 150 miles. Beyond cars, we are deeply rooted in our community, actively supporting local initiatives such as ArtScape @ Your Library and the Toys for Tots program, reflecting our core values of service and generosity. Join us at our eco-friendly facility where we offer a host of amenities designed to make your visit comfortable and enjoyable, from our pet-friendly showroom and kids' playroom to complimentary snacks and beverages.
Related Articles:
Your Comprehensive Guide to Choosing a Toyota Dealer in Avon, IN